If you’ve been thinking about buying a home, you’ve probably noticed that mortgage rates have been getting a lot of attention lately.
As of October 1, 2026, Freddie Mac reported the average 30-year fixed mortgage rate at 7.28%. That's higher than it was just a few weeks ago, and it's understandable if you're wondering whether now is the right time to buy.
But there’s another side to the conversation that’s worth considering.
Higher Rates Don’t Tell the Whole Story
When mortgage rates rise, some buyers decide to wait. That can mean fewer buyers competing for certain homes.
The Mortgage Bankers Association recently reported a 4% decrease in purchase mortgage applications for the week ending September 25. While that doesn't tell us what will happen next, it does show that higher rates are affecting buyer activity.
For you as a buyer, less competition may create opportunities. Depending on the home, the seller and the circumstances of the sale, you may find more room to negotiate on price, closing costs or other terms.
Every situation is different, but it’s worth looking at the possibilities rather than focusing only on the interest rate.
Your Interest Rate Isn’t the Only Number That Matters
One thing I always encourage buyers to do is compare lenders.
Different lenders may offer different interest rates, points, fees and loan programs. A lower advertised rate doesn't necessarily mean a lower overall cost if you're paying more upfront through discount points or other fees.
You may also hear about buying down your interest rate. Discount points are upfront costs paid to a lender in exchange for a lower interest rate. Whether that makes sense depends on the cost, how much the rate is reduced and how long you expect to have the mortgage.
That's why it's important to look at the complete loan offer, not just the interest rate.
If you don't already have a lender, I'd be happy to refer you to a mortgage professional I trust who can help you compare your options and understand the numbers. You're always welcome to compare lenders, rates, loan programs and terms to find what works best for your situation.
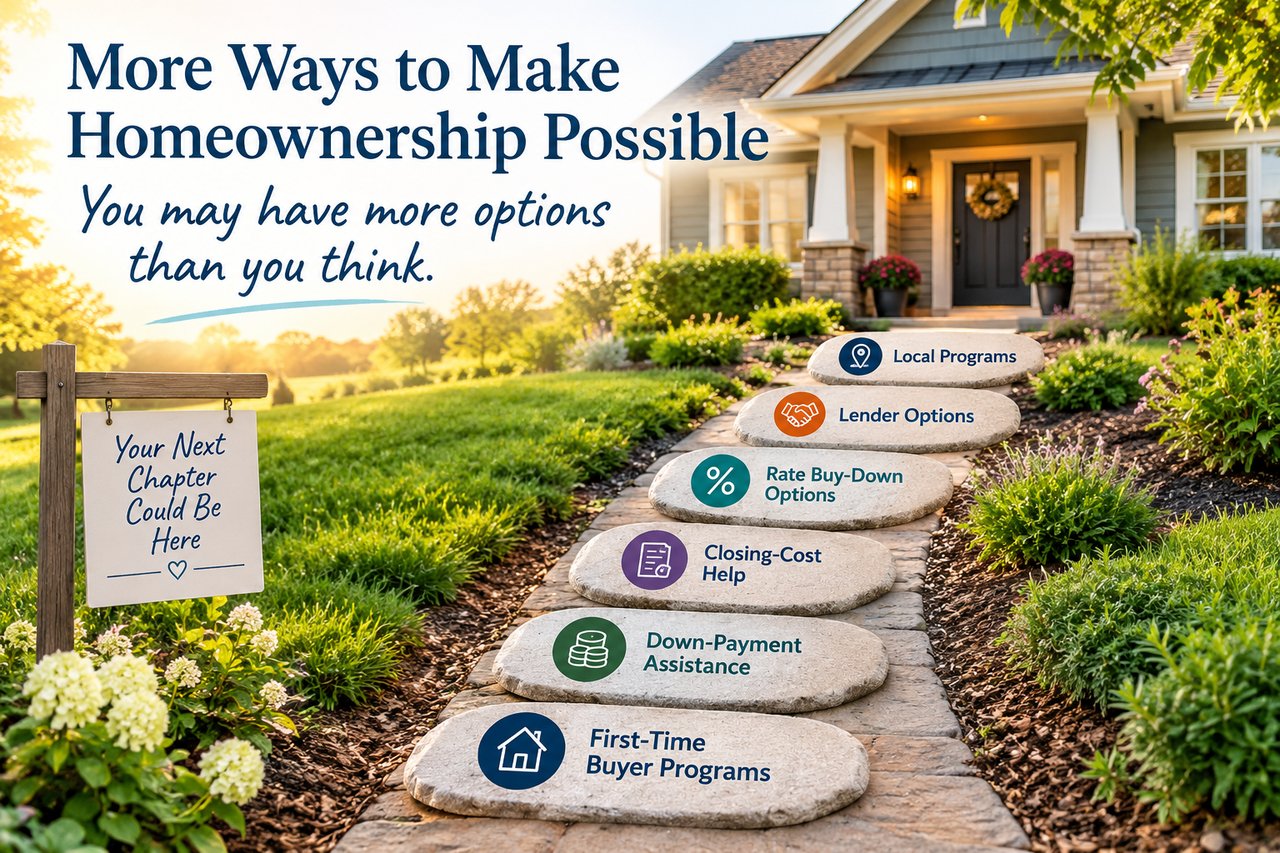
You May Have More Options Than You Think
If you're a first-time homebuyer, you may be surprised by the programs that could be available to help make homeownership more attainable.
Depending on where you're buying and your individual circumstances, there may be down-payment assistance, closing-cost assistance, first-time-homebuyer programs or even city- and neighborhood-specific programs available to qualified buyers.
Some programs may provide substantial assistance, but eligibility, funding and program requirements vary. That's why it's important to ask questions and find out what you may actually qualify for.
You may also want to talk with a lender about programs available through your state, local community or other organizations.
Before you decide you can't afford to buy, it may be worth finding out what options are available to you.
You may have more options than you realize.
Should You Wait for Rates to Come Down?
This is probably one of the biggest questions buyers are asking right now.
Waiting is certainly an option. But waiting for a lower rate can be a bit of a gamble, too, because no one knows exactly where mortgage rates are headed.
Rates could go lower. They could go higher. They could stay about where they are.
And while you're waiting, other things can change as well. Home prices can change. Inventory can change. Competition can change. And the home you really wanted might not still be available.
That's why I think it's helpful to ask a different question.
Instead of only asking:
“Will rates be lower later?”
Consider asking:
“What can I comfortably afford today, and what opportunities are available to me right now?”
That doesn't mean everyone should buy today. Your finances, your plans and your comfort level are what matter most.
But if you find a home that fits your needs and your budget, it may be worth exploring what buying looks like today, rather than making your decision based entirely on trying to predict the future.
You Don’t Have to Figure It Out Alone
Buying a home involves much more than finding the right property.
Financing, inspections, negotiations, closing costs and all the details in between can feel overwhelming — especially if you're buying your first home.
As a Realtor, I can help you navigate the real-estate side of the process and connect you with other real-estate professionals and resources you may need along the way.
You don't have to have everything figured out before you reach out.
Sometimes the first step is simply having a conversation and learning what your options are.
The Bottom Line
Mortgage rates are important, but they aren't the entire story.
Today's market may look different than it did a few months ago, and tomorrow's market may look different again.
You can't predict exactly what mortgage rates will do next. But you can understand your options.
You can compare lenders.
You can explore loan programs.
You can ask about buying down your rate.
You can find out whether you qualify for down-payment or closing-cost assistance.
And you can look at what homes and opportunities fit your budget today.
If you're thinking about buying or selling, I'd be happy to talk with you about what's happening in the local market and help you explore your options.
Because it's not just about buying a house.
It's about making a house a home.
— Anne